How to File a Roof Insurance Claim in Amarillo After a Storm
When a hailstorm rolls through Amarillo, the damage to your roof is only half the problem. The other half is the insurance claim, and that is where many Texas Panhandle homeowners lose money they were entitled to. A roof insurance claim in Amarillo can be straightforward or it can turn into a drawn-out fight, and the difference usually comes down to what you do in the first few weeks after the storm.
Valdez Roofing works with Amarillo homeowners through the claims process regularly, documenting damage and working alongside insurance adjusters. This guide walks through how the process actually works, the deadlines that can quietly cost you coverage, and the mistakes that lead to denied or underpaid claims.
Start With Documentation, Not a Phone Call
The most important step in a roof insurance claim happens before you contact your insurer. Document everything first. Strong documentation is what separates a smooth claim from a disputed one.
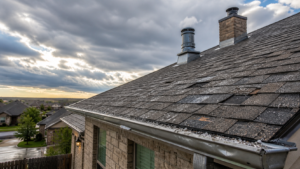
After the storm has passed and it is safe to do so, take clear, timestamped photos and video of any visible damage: dented gutters, damaged screens, debris, and anything on the roof you can see from the ground. Note the date of the storm, because in Texas the claim clock starts on the date of loss, not the date you notice a leak.
Then get a professional roof inspection before the adjuster arrives. An independent inspection from a local roofer establishes the scope of the damage on the record, in your favor, before the insurance company forms its own opinion. This is the single most valuable thing you can do, because it means the adjuster is not the only party defining what happened to your roof.
Know Your Deadlines Before You Need Them
Insurance deadlines in Texas are more complicated than most homeowners realize, and missing one can end a valid claim. There are really two clocks running.
The first is your policy’s notice-of-loss deadline. Your homeowners policy is a contract, and it requires you to report damage within a certain window. That window varies widely by carrier. Some require notice within 30, 60, or 90 days, while others allow up to a year. This deadline is legally enforceable, and reporting late gives your insurer grounds to reduce or deny the claim.
The second clock is the Texas statute of limitations, which under state law generally allows up to two years from the date of loss to take legal action against an insurer. That two-year figure is the outer legal boundary for a lawsuit, not a license to wait. Your policy’s reporting window almost always closes long before then.
The practical takeaway is simple. Do not wait. Report significant storm damage promptly, ideally within days to a few weeks, and check your declarations page or call your agent to confirm your exact reporting window.
The Claim Process, Step by Step
Once your damage is documented, the claim itself follows a fairly predictable path. Knowing the steps in advance keeps you from being caught off guard.
- Report the claim to your insurer and provide the storm date and your documentation.
- Your insurer assigns an adjuster, who typically inspects the property within one to two weeks.
- Request a joint inspection so your roofing contractor can be on-site while the adjuster evaluates the roof.
- The adjuster produces a damage estimate, which becomes the basis for your payout.
- Review that estimate carefully, and if damage was missed, your contractor can file a supplement with additional documentation.
The joint inspection step is worth insisting on. When your contractor and the adjuster walk the roof together, missed damage gets caught on the spot, and the back-and-forth that drags claims out is far less likely.
Why Panhandle Roof Claims Get Denied or Underpaid
Understanding why claims fail helps you avoid the traps. In the Texas Panhandle, most denied or reduced roof claims come down to a handful of recurring issues.
Late notice is the most common. Waiting too long to report gives the carrier a built-in reason to question the claim. Pre-existing damage is another, because adjusters look for ways to attribute damage to normal wear or an older storm rather than the recent event, which is exactly why dated, independent documentation matters so much. A third is the cosmetic damage exclusion that some Texas policies carry, which can limit coverage for hail damage that dents or marks the roof without causing a functional failure.
None of these are reasons to skip filing. They are reasons to file correctly, with documentation, on time.
Where a Local Roofer Fits Into the Process
Valdez Roofing has experience working with major insurance providers across the Amarillo area. We inspect the roof, provide detailed damage documentation, and can work directly with your insurance company throughout the repair process. You stay in control of your claim, and you have a knowledgeable local team making sure nothing gets overlooked. If you are not certain your roof was even damaged, it helps to know how to spot hail damage on your roof before you start.